Get Personal Loans up to 5 Lakhs in 10 minutes
Home > Personal Loan > ₹3 Lakh Personal Loan
Check your eligibility for a ₹3 lakh (₹3,00,000) personal loan on Zype for treatment, a rental deposit, card repayment, or a home project. Loans are available to salaried applicants, with repayment options from 6 to 36 months, subject to your offer.
Your reason for borrowing can shape your repayment plan. You may expect an insurance reimbursement, a deposit refund or repayments entirely from salary. Compare the five situations below, then review the EMI, fees and amount you will receive before accepting.
The average interest rate on a credit card is roughly 36% to 42% per year and is charged on the complete credit card balance. A personal loan taken from a loan app generally costs an interest rate from 18% to 34% per annum.
Say you owe ₹3 lakh in credit card outstanding and pay only the minimum due each month. Because the minimum due is a small portion of the total balance and the interest keeps piling up at a high interest rate, the outstanding barely moves and you stay in debt for years. When you pay the complete outstanding using the ₹3 lakh personal loan, the fixed EMI replaces the revolving balance, at a comparatively lower interest rate.
The ideal way taking a ₹3 lakh loan to repay credit card dues will work is when you don’t use the credit card for more spends during the loan repayment tenure.
A surgery, medical procedure, or treatment which is either not covered or partially covered by insurance can become a requirement for an urgent ₹3 lakh loan. In such a situation how soon you can get the loan become important.
On Zype, there is no prepayment or foreclosure charge, so there is no additional cost for closing the loan early. When the reimbursement lands, put it straight toward foreclosure or prepayment.
Weddings almost always cost a little more than what you budget, and a ₹3 lakh personal loan can often help you cover the gap when it comes to a venue booking, extra jewelry, or any other random cost that can come up last minute.
Make sure you only borrow for the gap between your savings and the budget because a larger EMI can have a long term implication on your monthly expenses.
In a metro city, a security deposit can be as high as ₹3 lakh, but you would get the amount back once your lease is over. That changes the math. You are bridging a gap for money that is coming back to you, not spending it for good.
A home renovation, purchasing new appliances, or setting up a new home can easily cost close to ₹3 lakhs. These are flexible and rarely urgent, which comes with both freedom and risk.
Choose the shortest tenure whose EMI you can comfortably manage. Since this is not an emergency, waiting and saving for a few months can help you borrow a smaller amount.
One thing to keep in mind across all the cases. Match the tenure to the nature of the expense, and only borrow an amount that is equal to the actual expense. The situation decides the right amount for the loan, not the other way round.
The table below shows an illustrative example of a 3 lakh personal loan EMI at a representative interest rate of 24% per year across the common repayment tenures. Use this table to understand the trade-off in each case, before you choose.
| Repayment Period (Tenure) | Monthly EMI | Total interest | Best suited for |
|---|---|---|---|
| 12 months | ₹28,368 | ₹40,415 | Rent Deposits, credit card clearing |
| 18 months | ₹20,011 | ₹60,191 | Weddings, credit card clearing |
| 24 months | ₹15,861 | ₹80,672 | Medical expense, home projects |
| 36 months | ₹11,770 | ₹1,23,715 | Lightest EMI, most interest |
*Illustration at interest rate of 24% a year on a reducing balance basis. Reducing balance means interest is charged only on the outstanding principal amount, not the full ₹3 lakh throughout the tenure. Your actual rate and EMI are disclosed in your Key Facts Statement(KFS) before loan disbursal.
Stretching from 12 to 36 months drops the EMI from about ₹28,368 to about ₹11,770, which can be more convenient to handle each month. But keep in mind that the total interest would be roughly three times, from about ₹40,000 to over ₹1.2 lakh, for the same ₹3 lakh loan amount. Choose the shortest tenure with an EMI you can manage.
On Zype, the interest rate ranges from 18% to 34% per year. The processing fee is a one-time charge, which is a percentage of your loan amount and is between 2% to 6% plus 18% GST on the processing fees. On a ₹3 lakh loan that is roughly ₹7,000 to ₹21,000 depending on what processing fee is offered to you. This charge is deducted from the loan amount before the net amount is disbursed to your bank account.
One advantage of taking a loan Zype loan is that there is no additional charges to foreclose the loan or prepay your EMIs. This means you can close the loan ahead of schedule. So, a bonus at work or a refund of your rental deposit can help close the loan and save the interest cost of the remaining tenure. Close a three-year ₹3 lakh loan at the one-year mark, and you save roughly ₹60,000 in interest.
Borrow for the actual need, and do not get enticed by a loan offer that might be higher than the amount you need. About 4 in 10 Zype borrowers take less than the limit they are approved for, choosing a loan amount that is as much as the expense in front of them. Two quick checks get you to the right number.
Spare savings, partial insurance coverage, or family help can all shrink the gap between the actual cost of the expense and the amount you need to borrow.
If the real figure is ₹2.4 lakh, borrow ₹2.4 lakh, not ₹3 lakh, just because you’ve been approved for it. If your need sits at a different level, say you need a ₹2 lakh personal loan or a ₹4 lakh personal loan , you can check those pages to get a detailed breakdown of the cost.
Paperless, yes. Verification-free, not quite. On Zype, you do not require any salary slips or paperwork, but your income and credit profile are still assessed to check your loan eligibility. For ₹3 lakh personal loan, a lender has to be confident that you can repay the loan on time. So, more often than not, an offer of that size without documents is a warning sign.
Aadhaar is used by lenders to complete the mandatory KYC. The actual loan eligibility and reporting requires your PAN details. So it is unlikely you can get a ₹3 lakh personal loan with only your Aadhaar.
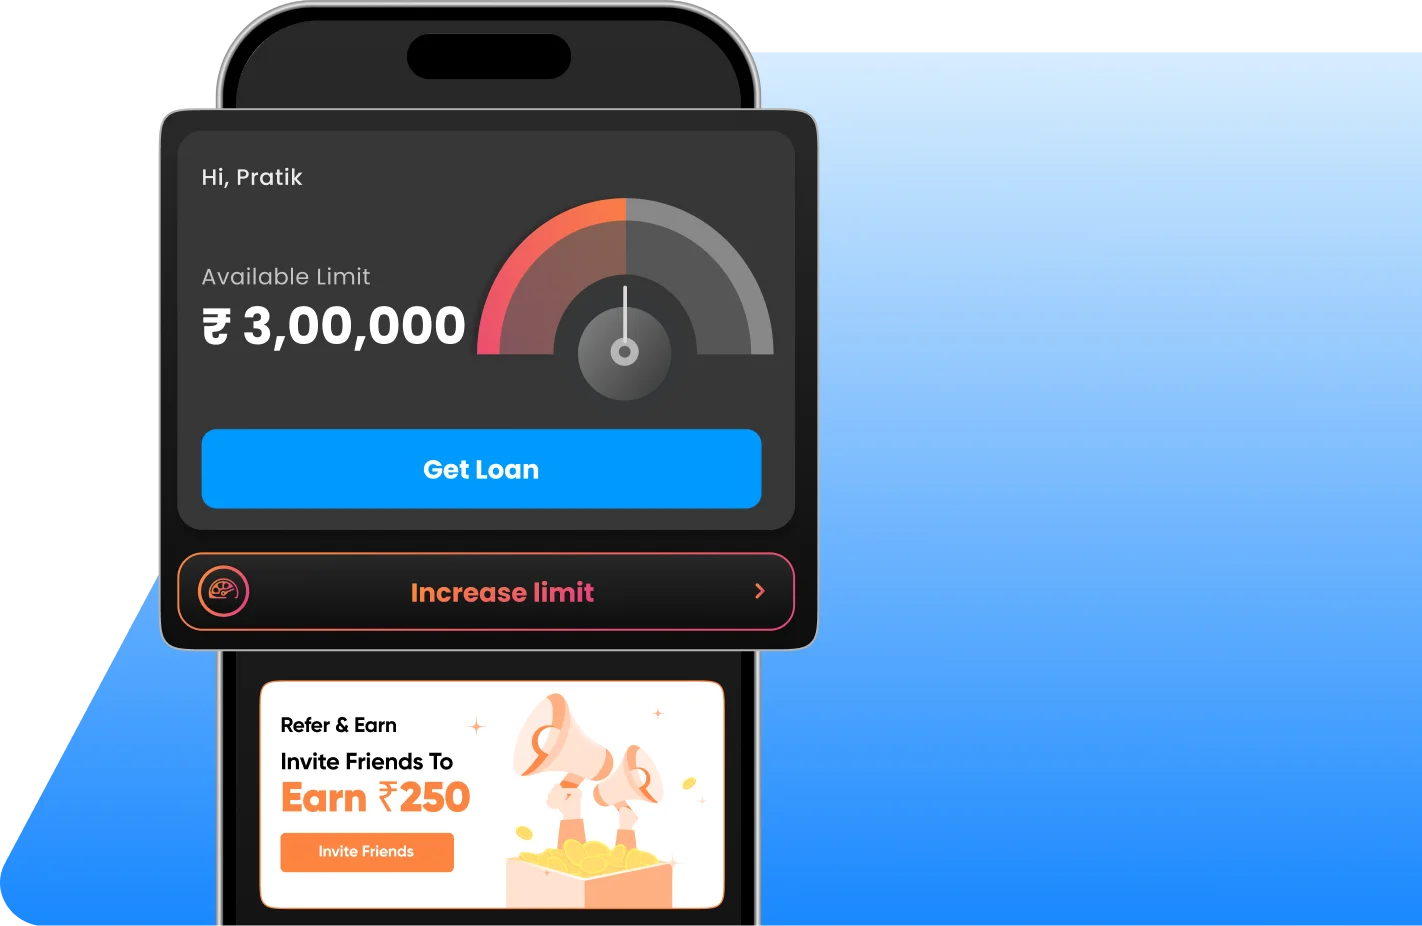
And on speed: the approval decision on the Zype app is instant, and after you accept the loan offer, the money usually lands in your account within minutes, subject to verification. The process is 100% digital and doesn’t require any documents apart from your PAN and Aadhaar details.
Whichever situation brought you here, these are the fixed details behind a personal loan upto 3 lakh, on Zype.
An EMI for a ₹3 Lakh personal loan is significant, so in practice an income near ₹40,000 or more makes getting the amount realistic. Self-employed individuals, freelancers, and full-time students without a salaried job are not eligible.
Interest rate ranges between 18% to 34% per year, charged on a reducing balance basis, plus a one-time processing fee between 2% to 6% including 18% GST (about ₹7,000 to ₹21,000 on ₹3 lakh), which is deducted from the amount before it is disbursed. The interest rate and processing fee offered are based on your credit profile and eligibility. No foreclosure or prepayment charge, ever, and no lock-in.
PAN and Aadhaar. No salary slip. Uploading your bank statement is optional if you want a higher loan amount than the one offered.
Complete the application with your PAN, personal and employment details. A loan offer is generated based on your eligibility. The loan amount gets credited to your account, after completing KYC and acceptance of the loan agreement.
Clearing a high-interest credit card balance can make a personal loan worthwhile. A personal loan may offer a lower rate and fixed EMI. However, it is advisable to limit credit card usage after clearing the balance.
The rule of thumb should be choosing the shortest repayment tenure where paying the monthly EMI is affordable and comfortable after accounting for all other ongoing EMIs and monthly expenses.
Technically, yes. You can get a ₹3 lakh loan without documents, but that does not mean there are no checks. Your income and credit profile are verified digitally using your PAN and Aadhaar details during application. A ₹3 lakh loan offer with no checks at all is probably a warning sign.
No, Aadhaar is only used for KYC verification after your loan is approved. Your PAN details are always required to check you credit profile and also to report your loan the credit bureaus. It is very unlikely that ₹3 lakh is given by a regulated lender on Aadhaar alone, and you should be cautious of any lender who claims otherwise.
The minimum income criteria on Zype is ₹15,000 a month. But a ₹3 lakh realistically needs more income, because the EMI is fairly significant event at a longer repayment tenure. At a rate of interest of 24% per annum and repayment period of 24 months, the EMI is about ₹15,861. This points to a monthly income near ₹40,000 or above for the EMI to be paid comfortably along with your other monthly expenses.
Yes, the process is 100% digital, from application to loan disbursal on Zype. Keep your PAN and Aadhaar details along with access to your mobile number linked to your Aadhaar, for a faster application.
It depends on the terms of your loan which you can check in the Key Fact Statement. On Zype, you can close the loan anytime. There are no foreclosure or payment charges, and there is no minimum lock-in period. You pay interest that is calculated only up to the day you close the loan. On a three-year loan closed after a year, you can save around ₹60,000.
A bank may offer a lower interest rate, but usually with slower processing, a possible minimum lock-in period on the tenure, and prepayment or foreclosure charges. If you have a strong profile, can wait for sometime to get the loan, and don’t intent to close the loan early, a bank can save interest cost. But loan apps like Zype are faster and fully digital. On Zype, especially, there are no prepayment or foreclosure charges, and it gives you the flexibility to close the loan early to save interest cost.
Not on Zype, where the longest tenure is 36 months. At 18% a year, a ₹3 lakh loan over 36 months has an EMI of about ₹7,618.
Personal loans on Zype carry an interest rate of 18% to 34% per year, calculated on a reducing balance, and the rate you are offered depends on your credit profile as assessed by the RBI-registered NBFC that disburses the loan. A processing fee of 2% to 6% of the loan amount, excluding 18% GST, is deducted at disbursal and also depends on your profile. There are no charges for foreclosure or prepayment, and there is no lock-in period. Your EMI, all applicable charges, the amount you will receive and the total repayment are disclosed in the Key Fact Statement, which you can review before the loan is disbursed.
Loans are disbursed via RBI-registered NBFCs. Zype is operated by Easy Platform Services Private Limited.